Built for the economics of a lease
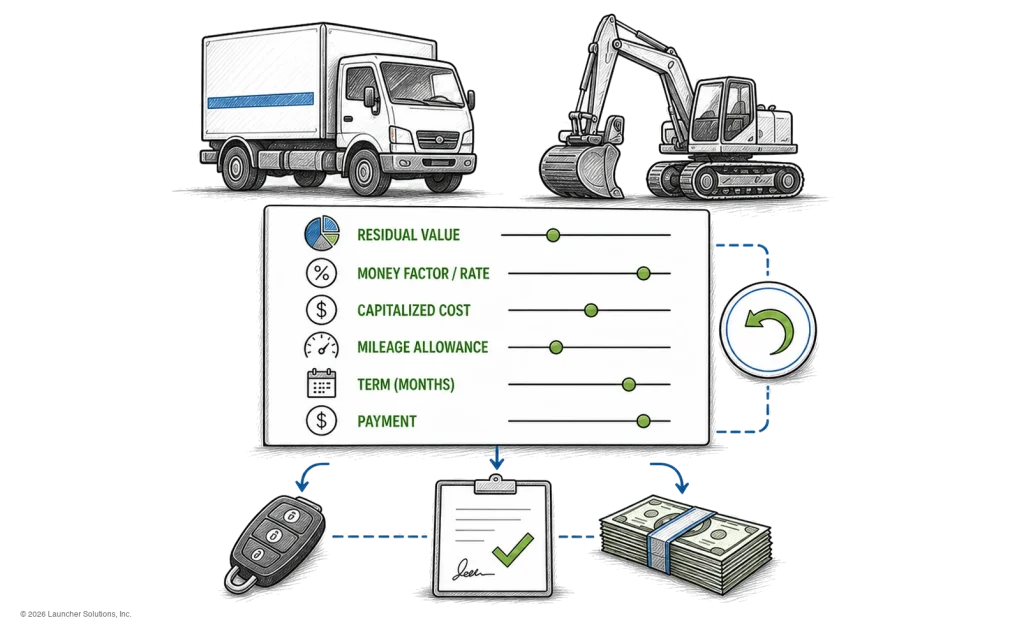
appTRAKER models residuals, money factors, capitalized cost, mileage provisions, purchase options and lease-specific documents as first-class origination data. It keeps those details with the applicant, asset, dealer and credit decision from application through funding.
A lease record can carry the values that drive both credit and structure:
Configured calculations and rules can use those values to test program fit, price the transaction and route exceptions for review. autoBUILT can evaluate permitted structural alternatives where the lender allows them.
Loans and leases can share a platform
A lender can originate loans and leases in appTRAKER while keeping separate programs, calculations, approvals, documents and workflows for each finance type. Teams use a common operating environment while preserving lease-specific economics, workflow, calculations and documentation.
Dealer-originated leasing
Lease applications can enter through Dealer Portal, Dealertrack, RouteOne, APIs and other supported channels. Applicant, asset and lease information then follows the lender appTRAKER underwriting process, including decisions, permitted deal changes, stipulations and documents.
myDEALER holds the dealer relationship behind those transactions, and myLOAN covers lease programs a lender originates directly rather than through a dealer.
Credit, collateral and verification
Lease underwriting can combine bureau data, scores, income, DTI or PTI, asset information, residual, payment, program eligibility and fraud or identity signals. Automotive programs may also use VIN, mileage, MSRP, valuation and other vehicle intelligence from supported providers.
Rules can process straightforward applications and identify transactions that need additional authority or human review. autoBOUGHT applies the configured decisioning; Fraud Intelligence brings the identity and fraud signals together in one view.
Documents through funding
DOCS & FORMS
Assembles lease agreements, disclosures, state and lender forms, supporting documents and Form Packs. Supported eSign services can participate where configured.
CONNECT
Keeps applicant and dealer SMS and email activity attached to the lease transaction through document collection and funding.
Stipulations and completed files remain attached to the transaction, so staff can see what was requested, what was received and what is still outstanding before funding.
Where leasing fits
appTRAKER can be configured for automotive, powersports, marine and recreational-vehicle, equipment and commercial-equipment lease programs. Each program retains the asset data, residual method, pricing and documents appropriate to it.
Why appTRAKER for leasing?
Build leasing around your strategy
Different lease programs require different assets, residuals, pricing, structures, credit policies and documents.
appTRAKER gives lenders a configurable platform for putting those requirements into one connected origination process.
appTRAKER
Configurable, scalable loan origination built around your products, channels and credit policy.
Explore →myDEALER
Dealer relationship management, built into the origination workflow.
Explore →myLOAN
A branded online application experience that feeds straight into appTRAKER.
Explore →autoBOUGHT
Your virtual underwriter — automated, 24/7 credit decisioning.
Explore →launchPAD
Essential origination tools for startup lenders and new programs.
Explore →Fraud Intelligence
Identity, phone, location, address, and bureau signal intelligence at the point of decision.
Explore →Dealer Portal
Give your dealer network one connected place to submit, work, and close deals with your lending team.
Explore →CONNECT
Two-way SMS and email between your lending team and applicants, tied to the loan.
Explore →autoBUILT
Configurable workflow automation for your origination process.
Explore →appTRAKER DOCS & FORMS
Document management, form generation, Form Packs and eSign — built into the LOS.
Explore →Frequently asked questions about lease origination
Can appTRAKER support both loans and leases?
Yes. They can run on the same platform while using different finance-type programs, calculations, rules, workflows and documents.
Can appTRAKER calculate lease payments?
Lease calculations can incorporate residual, term, money factor or rate, capitalized amounts, reductions, taxes, fees and other configured values.
Where do residual values come from?
Residual values and residual percentages are lender-defined and can be configured by program, asset, term and other lender criteria. Supported collateral and valuation data can participate wherever the configuration calls for it.
Can pricing vary by credit tier or lease program?
Yes. appTRAKER rules and configuration can support lender-defined pricing, programs, credit tiers, approval requirements and exceptions.
Does appTRAKER support dealer-originated leases?
Yes. Supported channels include Dealer Portal, Dealertrack, RouteOne, APIs and other configured integrations.
Can appTRAKER support leases for assets other than automobiles?
Yes. appTRAKER can be configured for lender-defined asset categories including powersports, marine, recreational vehicles, equipment, commercial equipment and other assets.
How are lease stipulations handled?
Stipulations and required conditions stay attached to the lease transaction from decision through funding, and supporting documents can be received from the applicant or the dealer.
Does appTRAKER service leases?
appTRAKER manages lease origination through funding and boarding. Ongoing account servicing remains with the lender servicing or core system.